
B9: Cash Advance
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
B9: Cash Advance - Screenshots
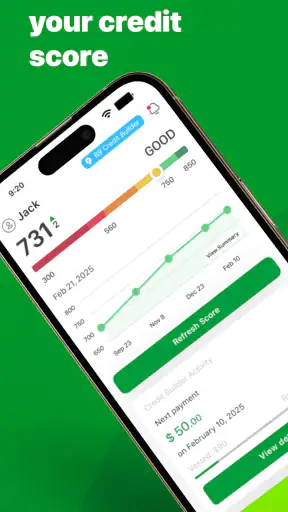
Pros
- Fast access to small cash advances between paychecks
- No traditional credit check required for many applicants
- Transparent repayment date shown before accepting an advance
- Useful budgeting tools can help track spending and upcoming bills
- Funds may arrive quickly through supported delivery options
Cons
- Advance limits may start low and increase gradually
- Express funding and optional services can involve extra fees
- Eligibility and availability vary by state and user history
- Repayment is typically automatic
- which can strain a tight budget
- Late or failed repayments may affect future access to advances
B9: Cash Advance - Description
- App Name
- B9: Cash Advance
- Package Name
- com.b9.app
- Developer
- B9 - Get Your Paycheck Early
- Category
- Finance
- Last Updated
- Aug 3, 2021
- Version
- 3.71.0
When an unexpected expense appears before payday, the appeal of B9: Cash Advance is easy to understand. It is a finance app from B9 - Get Your Paycheck Early that focuses on accessing part of your paycheck ahead of schedule, rather than asking you to manage a full budget, investment portfolio, or traditional loan. I approached it as a practical emergency tool, and my first impression was that its value depends less on novelty than on whether it fits comfortably into the way you already receive and plan your income.
The app is free to install and is rated for Everyone, which makes the initial barrier fairly low. It has built a substantial audience, with over one million installs, an average rating of 4.6, around eighteen thousand ratings, and roughly seven thousand five hundred written reviews. Those figures suggest that the basic idea is clear to many users, but they should not be mistaken for a guarantee that every person will qualify for or enjoy the same experience. A paycheck advance is useful only when the timing, eligibility, repayment expectations, and total cost make sense for your own situation.
From first-week appeal to long-term usefulness
Why the first week feels immediately practical
The strongest part of the first-week experience is the narrow purpose. B9 is not trying to become your entire financial life. Its central promise is straightforward: help you get a cash advance before payday. That focus can be reassuring when the problem is equally straightforward, such as covering a necessary purchase or handling a bill that arrives a few days earlier than your normal income.
I also like the fact that the app is positioned as a recurring paycheck-access tool rather than a one-off search for a lender. In a stressful moment, reducing the number of decisions matters. Instead of comparing several unrelated borrowing products, a user can start by checking whether this particular service fits their income arrangement. That makes the app easier to understand than many finance apps that combine credit, savings, investing, insurance, and banking features in one crowded interface.
A realistic example would be a worker whose paycheck arrives at the end of the week but whose car needs a necessary repair on Tuesday. If the user is eligible and the advance terms are acceptable, B9 may bridge that short gap more cleanly than missing work or allowing a critical payment to fail. The advantage is not that the app makes the expense disappear. Its advantage is timing: it can move access to earned income closer to the moment when the expense occurs.
That distinction is important. I would not treat a paycheck advance as extra money. I would treat it as money arriving earlier, with the next payday still needing to support the rest of the month. This mindset is one of the most useful habits to establish during the first week. Before requesting an advance, I would write down the upcoming payday amount, fixed bills, food and transport costs, and any other automatic withdrawals. If the advance leaves the following pay period too tight, the short-term relief may simply move the problem forward.
What to check before relying on an advance
The first-week setup should be approached like a financial decision, not like activating a casual convenience app. Read the displayed terms carefully before confirming anything, especially the amount you can access, when funds should arrive, and what the service expects around repayment. The exact details that appear for one user may not be identical for another, so I would never base a decision on a friend’s experience alone.
Another practical step is to test the app against your real payday routine. Ask yourself whether your income is predictable enough for an advance to remain manageable. Someone paid on a stable schedule may find the timing easier to plan than someone whose hours, tips, or deposits change frequently. The app may still be useful for the latter group, but uncertainty makes it more important to leave room for ordinary expenses and not request the maximum simply because it is available.
One non-obvious trade-off is that convenience can make borrowing feel smaller than it really is. A few taps may remove the emotional pause that normally happens when someone has to visit a bank, speak with a lender, or transfer money manually from savings. I see that as both a strength and a risk. The smoother the process feels, the more deliberately I would create my own pause: check the next payday budget, confirm the advance is for a necessary purpose, and decide how the repayment will affect the following week.
How it compares with ordinary alternatives
Compared with waiting for payday, B9 can be more useful when the expense is urgent and delaying it would cause a bigger problem. Compared with overdrawing a bank account, a paycheck advance may feel more intentional because the user requests access to income rather than hoping a transaction clears. However, neither option should be judged by convenience alone. The important comparison is the total financial consequence, including any applicable charges, timing issues, and the effect on the next pay cycle.
A traditional personal loan may be more appropriate for a large, planned expense that cannot reasonably be covered by one paycheck. A credit card may offer a better fit for someone who can repay a purchase without carrying a balance, while a savings account is usually the healthier first choice when an emergency fund is available. B9 occupies a narrower space: short-term access to pay for people who need timing flexibility, not a replacement for long-term borrowing or regular saving.
That narrow positioning is why I would recommend comparing the app with your own alternatives before using it. If you can safely wait, use existing savings, or rearrange a bill without creating new costs, those options may be better. If the alternative is a costly late payment or an essential expense going unpaid, the advance may have a clearer justification.
Month-to-month value depends on the habit it creates
After the initial appeal fades, the real question becomes whether B9 helps you manage timing occasionally or encourages a permanent cycle of catching up. I think the app earns lasting value when it remains an emergency buffer used with a clear reason. It becomes less attractive when every payday is planned around taking an advance because the regular income no longer covers ordinary spending.
My preferred workflow would be to use the app only after checking the next two weeks rather than looking at the current balance in isolation. Record the advance in the same place where you track bills, mark the expected effect on payday, and review whether the original expense was genuinely unavoidable. This creates a small feedback loop. If the same category keeps forcing an advance, the long-term solution may be changing that expense, adjusting the budget, or building a small reserve instead of repeatedly moving pay forward.
This is one of the app’s more important practical limitations: the service can solve a cash-flow gap, but it cannot repair a persistent income-versus-expenses gap. If rent, utilities, food, and transport regularly consume nearly all of your pay, an advance can provide relief while making the next pay period even more constrained. In that situation, a conversation with a nonprofit financial counselor, an employer, or the bill provider may be more useful than another advance.
The recurring value is stronger for people with occasional timing problems. For example, a user might have a predictable paycheck but an annual insurance payment, school expense, or unexpected household repair that falls at an inconvenient point in the pay cycle. Used selectively, B9 can be a tool for smoothing that mismatch. Used automatically every month, it risks becoming part of the problem rather than a temporary solution.
Maintenance: the work the app cannot do for you
The app itself may reduce the effort needed to request an advance, but maintaining a healthy relationship with it still requires personal organization. I would review the account before each request, keep notifications or account messages visible, and avoid assuming that a previous advance amount will always be appropriate. Your income, bills, and eligibility circumstances can change, so repeating an old routine without checking the current situation is careless.
There is also a useful distinction between maintaining the app and maintaining the financial plan around it. Updating an application is basic maintenance; knowing what will happen to your next paycheck is the important maintenance. B9’s current version is 3.71.0, and it supports devices running Android 8.0 or later. That makes compatibility reasonably accessible for many Android users, but a supported operating system does not remove the need to keep your login, income information, and personal budget organized.
I would also avoid treating the app as a substitute for a separate emergency fund. Even a modest reserve gives you more control because it does not depend on moving future income forward. A sensible long-term routine could be to use an advance only when necessary, then direct a small amount toward savings when the next few paychecks are comfortable. The goal is not to make B9 part of every payday; it is to make the need for it less frequent.
One useful advanced habit is to separate “timing emergencies” from “income emergencies.” A timing emergency means you can afford the expense once payday arrives, but the bill comes first. An income emergency means the income itself is insufficient. B9 may address the first category, but it cannot solve the second. Making that distinction before requesting money prevents the app from being used for a situation that requires a broader solution.
Where long-term fatigue can appear
The first source of fatigue is repetition. What feels helpful once can feel restrictive when it becomes a monthly ritual. Each request requires another review of the upcoming pay cycle, and that mental load can grow if the user is already worried about money. The service is most comfortable when it reduces a rare inconvenience, not when it becomes the centerpiece of household cash management.
A second source is uncertainty around personal availability and timing. Users naturally want to know exactly how much they can access and when it will arrive, but financial services often depend on individual circumstances and account details. I would therefore avoid making a time-sensitive payment based solely on the hope that an advance will appear quickly. If a missed deadline would create a serious consequence, confirm the current terms inside the app and keep a backup plan.
A third issue is psychological: early access can blur the boundary between earned income and discretionary spending. When money becomes available earlier, it is tempting to treat that availability as increased spending power. I found the safer approach is to label the advance mentally as “already committed to payday.” That simple rule protects the next pay cycle from being mistaken for a fresh source of money.
There is also a reason some users should skip B9 entirely. If you already have a reliable emergency fund, can wait for payday, or have access to a lower-cost option, the convenience may not justify adding another financial service to your routine. Likewise, if your income is so irregular that you cannot confidently predict the next pay period, an advance may create more pressure than it removes. In those cases, a savings strategy, employer-based option, or carefully assessed traditional product may be a better fit.
Privacy and trust deserve attention as well. This is a finance app, so I would read every permission, identity, income, and account request shown during setup instead of accepting screens automatically. I would also use only the official app source and verify that the developer name displayed is B9 - Get Your Paycheck Early. Those checks are simple, but they matter more for a financial product than they do for a casual game or utility.
Who gets the most value from it
I see B9 as a good match for an adult who receives regular pay, occasionally faces expenses before payday, and is willing to track the effect on the next check. The Everyone content rating makes the app broadly accessible from a store-classification perspective, but the financial responsibility involved is still very much an adult decision. The ideal user is not looking for free money; they are looking for controlled timing flexibility.
It can also suit someone who dislikes the complexity of larger financial platforms. Because the app’s identity is centered on paycheck access, its purpose is easier to explain to a friend: use it when the timing of earned pay is the problem. That simplicity is valuable if you do not need investment tools, extensive budgeting dashboards, or a full banking replacement.
I would be more cautious recommending it to someone who is already using advances to cover groceries, rent, or utilities every pay period. That pattern suggests the issue is structural. The app might still provide immediate relief, but the lasting answer would involve reducing expenses, increasing income, renegotiating bills, or finding professional support. A convenient interface should never disguise that distinction.
My long-term verdict
After the novelty of early access wears off, B9’s lasting value comes down to discipline and fit. It is not an app I would install simply because an advance is available. I would keep it in consideration for a specific cash-flow problem, then use it only after checking the next payday budget and understanding the current terms. That approach preserves its strongest quality: practical help at the right moment without pretending to be a complete financial plan.
The free price makes trying the app less intimidating, and its strong user response shows that the concept has connected with many people. Still, popularity does not replace personal arithmetic. The most important question is whether an advance makes the next pay period manageable or merely postpones the same pressure. If it does the former, the app can earn a sensible place in an emergency toolkit. If it does the latter, continuing to use it will likely create fatigue and dependence.
My recommendation is therefore conditional but positive. I would recommend B9: Cash Advance to someone with predictable income who needs occasional access to pay ahead of schedule and is prepared to treat each request as a planned financial decision. I would not recommend making it a default payday routine, using it for long-term shortfalls, or skipping comparisons with savings and lower-cost alternatives.
The lasting test is simple: use B9 to bridge an occasional gap, not to build your monthly budget around borrowed time. In that role, it is focused, understandable, and potentially useful. Outside that role, the convenience can become its biggest weakness.
FAQ
What is B9: Cash Advance, and how does it work?
B9: Cash Advance is a financial app designed to give eligible users early access to part of their expected paycheck, along with account and money-management features. After creating an account and completing identity verification, the app reviews your information and shows whether you qualify. Available advance amounts, timing, repayment rules, and other features can vary by user and may change over time.
How much money can I get through B9: Cash Advance?
The amount you may access through B9 depends on factors such as your income, employment details, account activity, eligibility status, and repayment history. The app displays your available limit before you accept an advance, so you can review the offer in advance. Do not assume that the maximum advertised amount will be available to every user, particularly when opening a new account.
Does B9 charge fees, interest, or a monthly subscription?
B9’s costs can depend on the plan and services selected. Some features may involve a membership fee, optional expedited delivery charges, or other account-related costs, while an advance may have different pricing from a traditional loan. Before confirming anything, carefully read the current fee schedule, subscription terms, repayment conditions, and cancellation policy shown in the app, because pricing and availability may change.
How quickly can I receive a B9 cash advance?
Delivery speed depends on factors including approval, verification, your linked bank account, payroll information, weekends or holidays, and the transfer method you choose. Standard transfers may take longer than an expedited option, and expedited delivery may cost extra. The app should provide an estimated arrival time before you confirm the transaction, but that estimate is not always a guarantee.
Is B9: Cash Advance safe, and what should I know before signing up?
B9 may request sensitive information such as your identity details, income information, bank connection, and employment data to provide its services. Review the privacy policy, permissions, user agreement, and eligibility requirements before registering. A cash advance can help cover a short-term gap, but it is not a long-term budgeting solution. Confirm repayment timing and total costs, and never share your login or verification codes.


